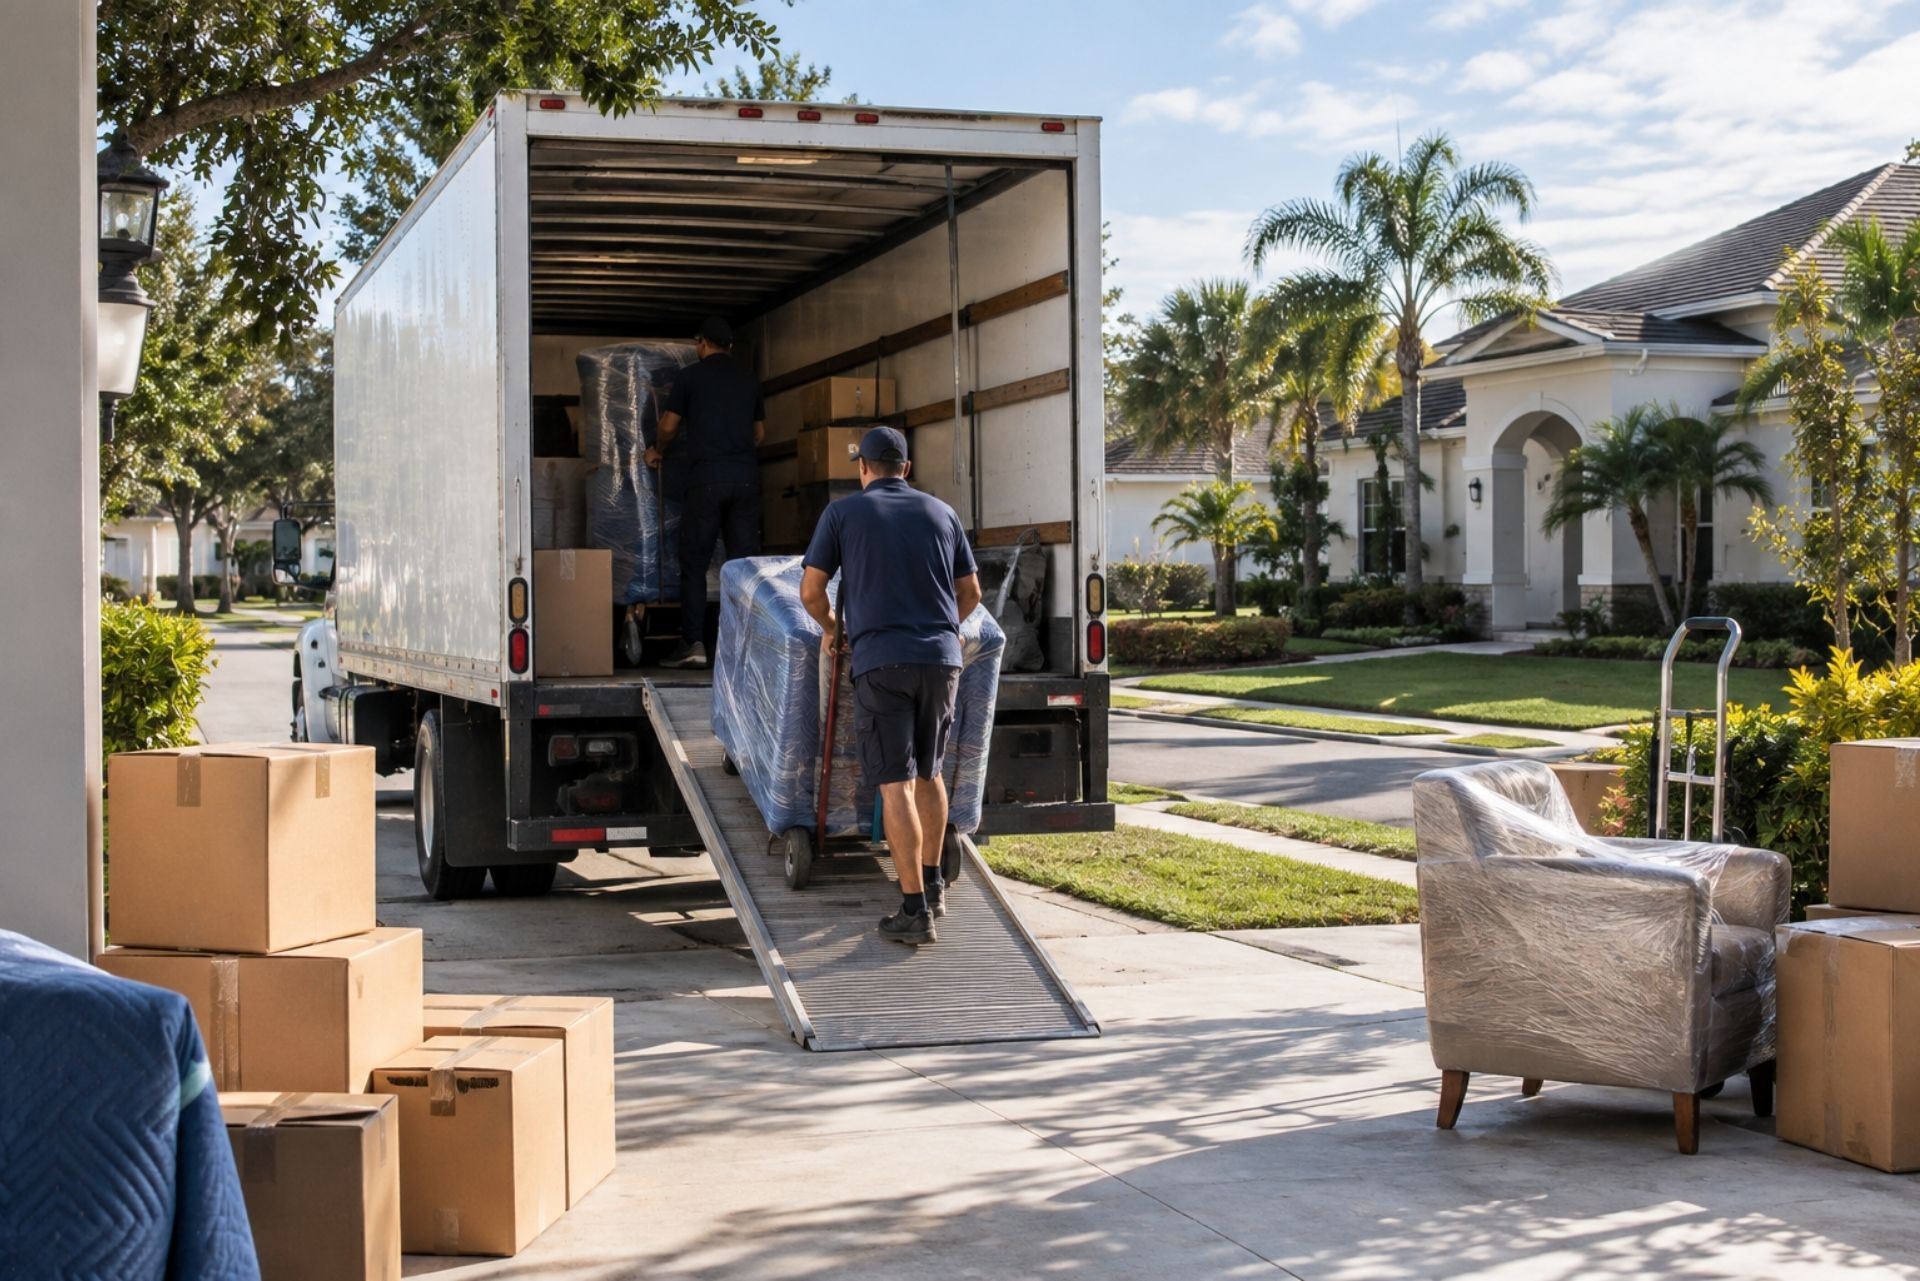
A single dropped dresser on a client's hardwood floor can cost a local mover $3,000 in damage claims. A truck backing into a parked car in a condo lot? That's another $8,000. And if a crew member tears a rotator cuff hoisting a gun safe up a narrow staircase, the workers' comp claim alone could run $25,000 or more. These aren't hypothetical scenarios: they're the kinds of calls that come into brokerages like Champion Risk on a regular basis.
Local moving companies face a unique collision of risks. You're operating heavy vehicles on residential streets, carrying strangers' most valued possessions, and sending crews into unfamiliar buildings where one wrong step can mean an injury or a lawsuit. Your standard homeowners policy won't help here: most homeowners policies cap personal property coverage for items in transit at roughly 10% of the policy limit, and that assumes the homeowner even has coverage at both addresses during the move.
If you run a local moving operation, or you're starting one, the insurance decisions you make in the first few months will shape whether your business survives its first bad day. This piece breaks down the
core coverage types, from cargo liability and commercial auto to workers' comp and certificates of insurance, along with what they actually cost in 2026.
Essential Insurance Coverage for Local Moving Companies
Essential insurance coverage for local moving companies is not a single policy but a stack of policies, each addressing a different exposure. Miss one layer, and a single incident can shut you down. The three non-negotiable coverages are commercial auto, general liability, and workers' compensation. Most states require at least two of these before you can legally operate, and many building management companies won't let your crew through the door without proof of all three.
General liability protects you when your crew damages a client's property or a third party's property during a move. Think scuffed walls, broken banisters, or a dolly that rolls into a neighbor's car. Policies typically start at $1 million per occurrence and $2 million aggregate, which is the minimum most landlords and HOAs will accept. The average annual cost for a moving company's general liability policy runs between $500 and $2,000, depending on revenue, crew size, and claims history.
Commercial Auto Insurance for Moving Trucks
Commercial auto insurance for moving trucks is mandatory in every state, and the FMCSA requires a minimum of $300,000 in liability coverage for intrastate movers, though many states set higher thresholds. If you're crossing state lines even occasionally, federal minimums jump to $750,000. Your personal auto policy won't cover a 26-foot box truck, period.
Premiums depend heavily on driver records, truck age, and the radius you operate in. A small fleet of two to three trucks in a mid-sized metro area might pay $8,000 to $15,000 per year for commercial auto coverage. Companies with newer drivers or MVR violations can expect to pay significantly more. One thing to keep in mind: physical damage coverage (collision and comprehensive) is separate from liability and adds another $1,200 to $3,000 per truck annually. Champion Risk often helps new moving companies structure their auto policies to balance deductibles against cash flow, which matters a lot in year one.
Workers' Compensation and Employee Safety
Workers' compensation and employee safety go hand in hand, and in nearly every state, workers' comp is legally required the moment you hire your first W-2 employee. Moving is classified as a high-risk occupation, which means your experience modification rate (EMR) and class codes will push premiums higher than a typical office job. Expect to pay between $8 and $15 per $100 of payroll for movers, depending on your state and claims history.
The real cost of skipping workers' comp isn't just the fine: it's the uninsured injury claim that hits your personal assets. A back injury requiring surgery can generate $50,000 to $100,000 in medical bills. Champion Risk has published a
detailed breakdown of how workers' comp protects small moving crews and what happens when coverage gaps exist. If you use
1099 subcontractors, verify they carry their own policies, because misclassification audits are increasingly common in the moving industry.
By: Mark Raby
Chief Executive Officer at Champion Risk & Insurance Services
Protecting the Goods: Cargo Legal Liability vs. Customer Property Damage
Protecting the goods means understanding two distinct types of exposure: liability for items you're hired to transport and liability for property you damage that doesn't belong to the customer. These are covered by different policies, and confusing them is one of the most common mistakes new movers make.
Cargo legal liability covers the household goods and commercial items you're physically moving. General liability covers damage to third-party property, like a building lobby, an elevator, or a neighbor's fence. If your crew drops a refrigerator through a client's floor and it crashes into the downstairs neighbor's apartment, you've triggered both coverages simultaneously.
Understanding Cargo Legal Liability Limits
Understanding cargo legal liability limits starts with the federal default. The FMCSA's minimum released value standard is $0.60 per pound per article, which means a 50-pound flat-screen TV worth $2,000 would only be covered for $30 under basic released value protection. That's not a typo. Most customers don't realize how little this covers until they file a claim.
Full value protection, by contrast, requires the mover to repair, replace, or pay the current market value of damaged items. Movers who offer full value protection typically carry cargo policies with per-shipment limits of $50,000 to $100,000 and deductibles ranging from $250 to $500. The premium for cargo coverage usually falls between $500 and $2,500 annually for a local operation, depending on the declared value limits you offer.
General Liability for Third-Party Property Damage
General liability for third-party property damage is what kicks in when your operations cause harm to someone else's property or person, outside of the goods being transported. A common example: your crew scratches a marble lobby floor while wheeling a piano through a condo building. The condo association files a claim against your company, and your general liability policy responds.
This coverage also handles slip-and-fall claims if a passerby trips over your moving blankets on a sidewalk.
Moving companies face these third-party risks daily, and claims from building management companies are surprisingly frequent. Your general liability policy is also where "completed operations" coverage lives, protecting you if a customer discovers damage after your crew has left the premises.
Comparison: Basic Released Value vs. Full Value Protection
| Feature | Basic Released Value | Full Value Protection |
|---|---|---|
| Cost to Customer | Free (included by law) | Additional charge, typically 1%-3% of declared value |
| Coverage Basis | $0.60 per pound per article | Current market value, repair, or replacement |
| Example: 50-lb TV worth $2,000 | Pays $30 | Pays up to $2,000 (minus deductible) |
| Deductible | None | Typically $250-$500 |
| Mover's Insurance Requirement | Minimal cargo policy | Higher cargo limits required |
| Customer Satisfaction Risk | High (frequent disputes) | Low (claims resolved fairly) |
The gap between these two options is enormous, and it's the single biggest source of customer complaints in the moving industry. Movers who only offer released value protection save on premiums but lose customers to bad reviews. Offering full value protection costs more to insure, but it builds trust and justifies higher per-move pricing. If you're positioning yourself as a professional, reputable mover, full value protection is the standard your customers expect.
Managing Certificates of Insurance (COI) for Building Requirements
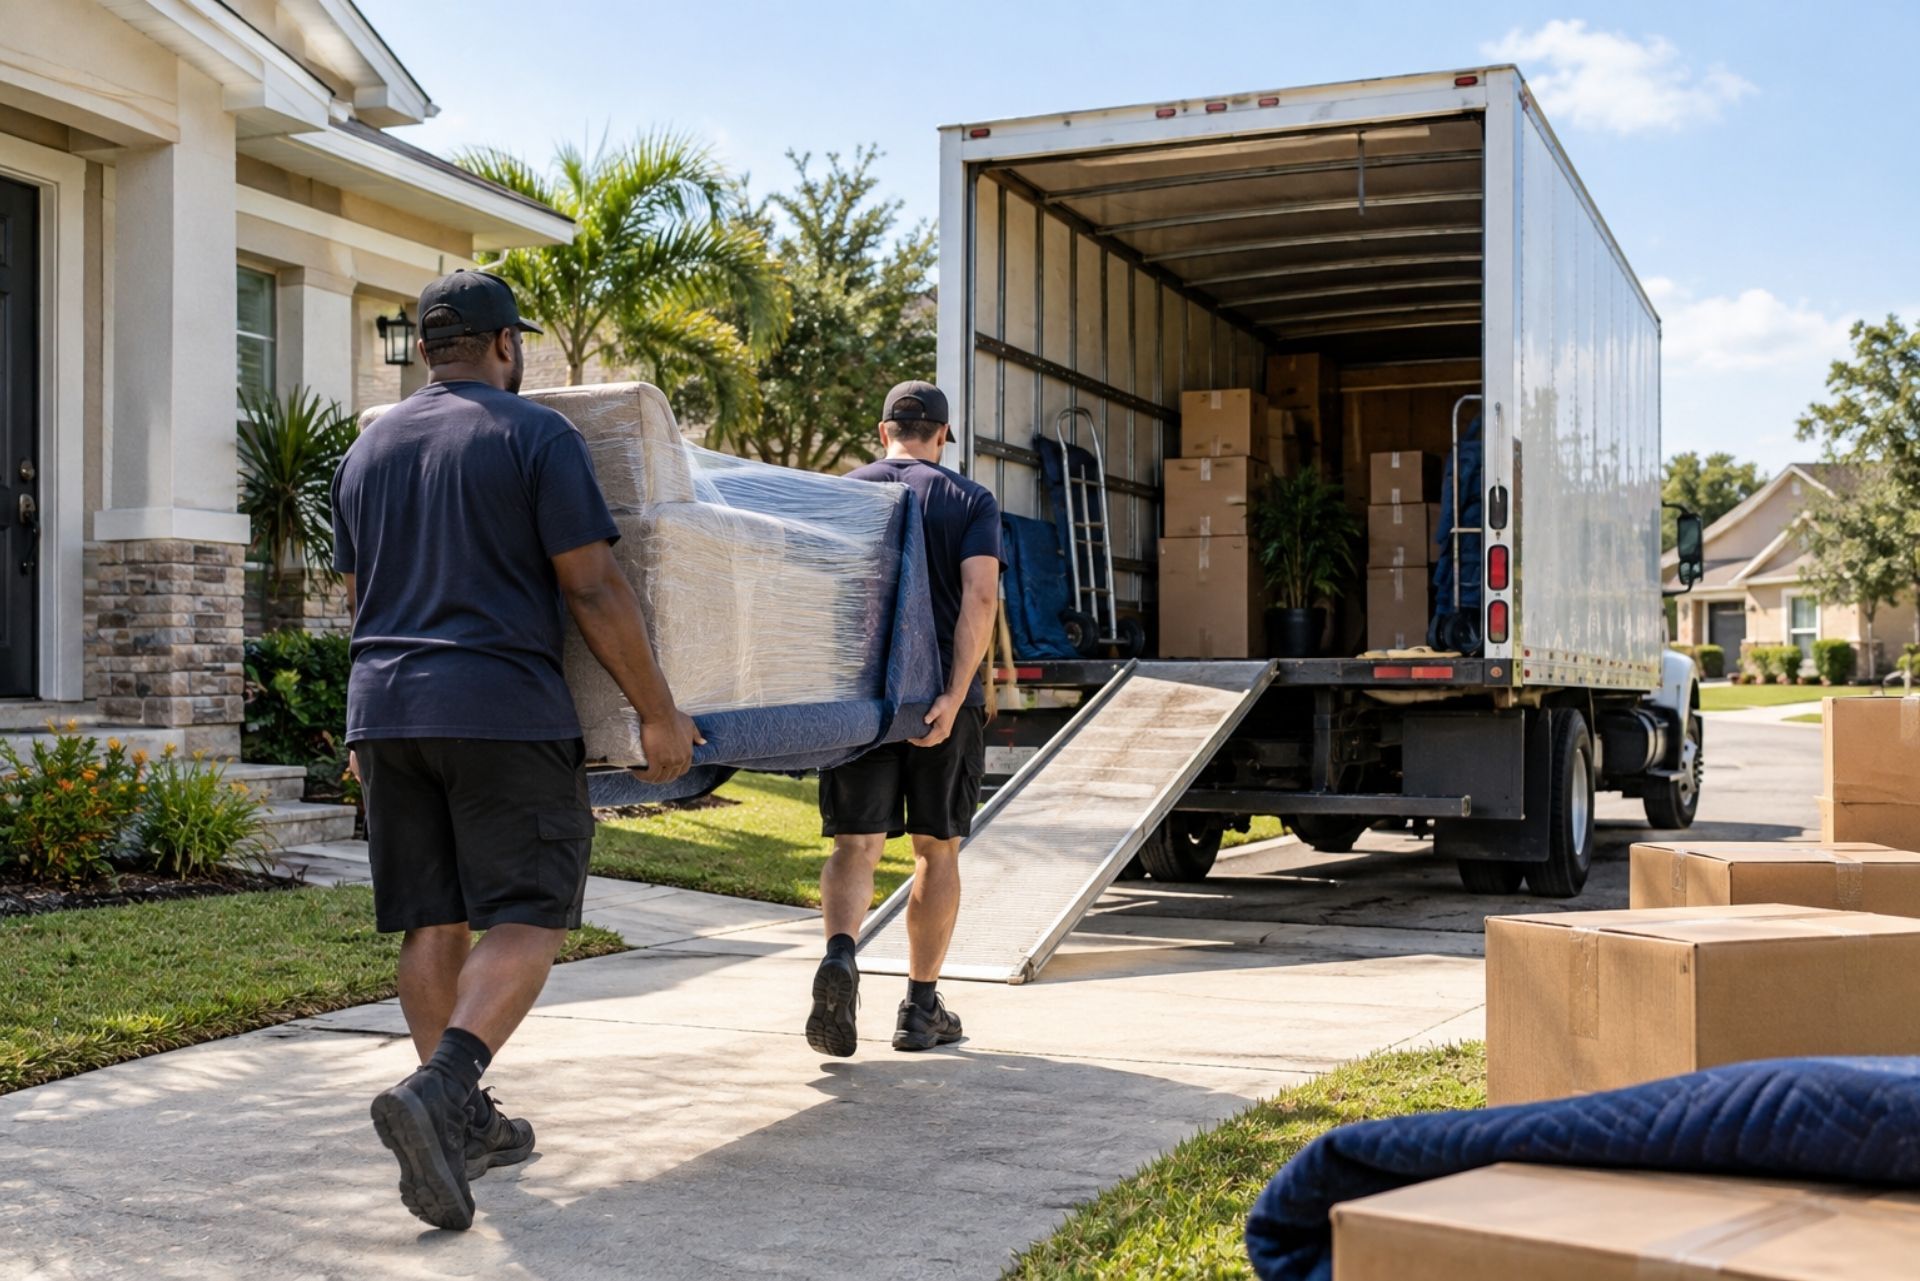
Managing certificates of insurance for building requirements is a daily operational headache for local movers, but it's unavoidable. Most apartment complexes, condos, and commercial buildings require a COI before they'll reserve an elevator or loading dock for your crew. A COI is a one-page document issued by your insurance carrier or broker that proves you carry specific coverages and limits.
The typical building requires your COI to show at least $1 million in general liability, with the building owner or management company listed as an "additional insured." Some high-rises in major metros demand $2 million or even $5 million in coverage. COI requirements vary widely by building, and last-minute requests are common: a customer books a move for Saturday, and the building manager emails COI requirements on Thursday afternoon.
Working with a broker who can issue COIs quickly makes a real difference. Champion Risk, for example, can typically turn around COI requests within 24 hours, which prevents the kind of scheduling disasters that cost movers revenue and reputation. Keep a digital template of your COI on file and ask your broker about blanket additional insured endorsements, which can eliminate the need for individual COIs for each building.
Factors That Influence Moving Insurance Costs
Several variables determine what you'll pay for a complete insurance package as a local mover. Your annual revenue is the primary rating factor for general liability: a company doing $500,000 in revenue will pay roughly double what a $250,000 operation pays. Fleet size and driver records drive commercial auto premiums. Payroll volume and your state's class codes determine workers' comp costs.
Here's a rough annual cost breakdown for a small local moving company with two trucks, five employees, and $400,000 in revenue:
- General liability: $1,000 to $1,800
- Commercial auto (two trucks): $10,000 to $18,000
- Workers' compensation: $8,000 to $15,000
- Cargo/inland marine: $800 to $2,500
- Umbrella/excess liability: $1,200 to $3,000
Total annual premiums for a small operation typically land between $20,000 and $40,000. That's a significant line item, but it's the cost of operating legally and protecting your business from a single catastrophic claim. Companies with clean loss histories and formal safety programs can often negotiate lower rates at renewal.
Common Questions About Local Mover Policies
FAQ: Coverage Basics and Claims
Does my personal auto insurance cover my moving truck? No. Personal auto policies exclude vehicles used for commercial purposes. You need a commercial auto policy rated for your truck's weight class and use.
What happens if a customer claims damage I didn't cause? Pre-move documentation is your best defense. Use timestamped photos and a detailed Bill of Lading to record existing damage before you load a single box. Your cargo insurer will investigate the claim based on this evidence.
Do I need insurance if I only use 1099 subcontractors? Yes. You still need general liability and commercial auto for any company-owned vehicles. You should also require proof of insurance from every subcontractor: if they're uninsured and get hurt, your company could be held liable.
Can I save money by raising my deductibles? Yes, but carefully. Raising your general liability deductible from $500 to $2,500 might save 10%-15% on premiums, but you'll pay more out of pocket on small claims. Balance the savings against your cash reserves.
Are antiques and high-value items covered under standard cargo policies? Most cargo policies have sub-limits for items like artwork, antiques, and jewelry. If you regularly move high-value goods, ask your broker about scheduling these items or purchasing a rider.
Is storage-in-transit (SIT) covered automatically?
Not always. SIT coverage applies when goods are temporarily stored, usually for 30 to 90 days, because a customer's new home isn't ready. This is often an add-on to your cargo policy, not included by default.
Before You Buy a Policy
The insurance stack for a local moving company isn't optional: it's the foundation your business stands on. Commercial auto keeps your trucks legal. Workers' comp keeps your crew protected. Cargo liability keeps your customers' belongings covered. And COIs keep building managers from turning your crew away at the door.
Before you sign any policy, get quotes from a broker who specializes in the moving industry. Generic business insurance agents often miss critical coverages or apply incorrect class codes, which can leave you exposed exactly when you need protection most. A firm like Champion Risk, with two decades of experience insuring movers, can audit your current coverage and identify gaps you might not know exist.
Start by documenting your fleet, payroll, revenue projections, and the types of moves you handle most often. Bring that information to your broker and ask specifically about cargo limits, additional insured endorsements, and your EMR. The right insurance program won't just protect you from disaster: it'll help you win contracts, satisfy building requirements, and sleep better knowing one bad move won't end your business.
About the Author:
Mark Raby
I am a seasoned insurance professional with over 30 years of experience in the industry. I lead Champion Risk & Insurance Services, a San Diego-based brokerage with nationwide reach and strong influence in the insurance marketplace. My core competencies include insurance agency M&A deals, captives and alternative risk structures, and commercial property and casualty insurance for clients in the transportation and logistics industries. I am a former president of IIAB San Diego and hold a Bachelor of Science in Finance from Western Michigan University’s Haworth College of Business.
Protection for Transportation Operations
Business Insurance for Transportation & Logistics Companies
Coverage designed specifically for transportation businesses
Commercial Auto & Trucking
Protection for your fleet including box trucks, moving vans, and trailers. Covers liability, collision, physical damage, and hired or non-owned vehicles used in your operations.
Motor Truck Cargo
Covers household goods and freight during transport from pickup to delivery. Protects against damage, theft, mysterious disappearance, and weather-related losses while cargo is in your care.
General Liability
Protection from third-party claims for bodily injury and property damage at customer homes, job sites, and your own facility. Essential coverage for every transportation operation
Warehouse Legal Liability
Coverage for customer property while stored in your facility. Protects against damage, theft, fire, and water damage to goods in your care, custody, or control.
Workers' Compensation
Medical care and wage replacement for employees injured on the job. Required in most states for transportation and warehouse work where physical labor creates higher injury risk.
Umbrella & Excess Liability
Higher liability limits stacked on top of your primary policies. Helps meet large contract requirements and protects your business assets against major claims and lawsuits.
Specialized Knowledge
Industries We Protect
Focused coverage for transportation and logistics businesses
Simple and Clear
How Our Process Works
Our process to get you covered
Connect With Us
Reach out through our form or by phone to share your business needs and current coverage situation.
Get Coverage Options
We review your risks, compare carriers, and present clear quotes with plain-language explanations.
Stay Protected
You choose your plan, and we provide ongoing support for certificates, claims, and renewals.
Trusted by Businesses
Feedback That Reflects Service and Reliability
What our clients say about working with Champion Risk
Answers You Need
Frequently Asked Questions
Common questions about transportation and logistics insurance
What insurance does a transportation company need to operate legally?
Motor carriers that cross state lines must meet FMCSA requirements. You need a minimum of $750,000 in liability coverage, plus a BMC-91 filing that proves your insurance to the federal government. Cargo coverage is also required, with minimums that depend on the type of goods you transport.
Intrastate operators follow state-specific rules. California, Texas, and Florida each have different requirements. Champion Risk handles both federal and state filings. We make sure your coverage meets legal minimums and your certificates reach the right agencies.
How much does commercial transportation insurance cost?
Premiums depend on your fleet size, driving records, cargo values, and claims history. A small operation with two trucks might pay $8,000 to $15,000 per year. A larger carrier with ten trucks could pay $50,000 to $100,000 or more.
The best way to control costs is working with a broker who knows transportation insurance. We find carriers that specialize in your exact operation type. This often results in better rates than going direct or using a general agent who doesn't understand the industry.
What is a BMC-91 filing and why do I need one?
A BMC-91 is a form your insurance company files with the FMCSA. It proves you carry the required liability coverage to operate as a for-hire motor carrier. Without an active BMC-91, your operating authority can be revoked.
Champion Risk works with carriers who file electronically. Your BMC-91 typically posts within 24 to 48 hours of binding coverage. We monitor your filing status and alert you if anything needs attention.
Does my warehouse or storage facility need different insurance than a trucking operation?
Yes. Storage facilities need warehouse legal liability coverage. This protects you when customer property is damaged or stolen while in your care. Standard general liability policies exclude this exposure.
You may also need property coverage for your building, equipment breakdown protection, and business income coverage if a fire or disaster shuts down operations. Champion Risk builds storage facility programs that address all these risks in one package.
Can you insure last-mile delivery drivers who use their own vehicles?
Yes. We offer hired and non-owned auto coverage for delivery operations that use independent contractors or employees driving personal vehicles. This fills gaps that personal auto policies don't cover during commercial use.
We also provide occupational accident coverage for 1099 drivers who aren't eligible for workers' comp. This protects your drivers and limits your liability exposure when accidents happen.
How fast can I get proof of insurance for a new contract?
Same day in most cases. Once we bind your policy, we issue certificates of insurance within hours. If your contract requires specific additional insured language or special endorsements, we coordinate directly with the carrier.
Rush requests happen often in this industry. General contractors and corporate clients demand certificates before they let you on site. Champion Risk prioritizes fast turnaround because we know your revenue depends on it.

Answers You Need
Transportation & Logistics Insurance Resources
Articles designed to inform and support your business
Contact Us
Phone Number:
Email Address:
Location:
12264 El Camino Real, Suite 350
San Diego, CA 92130
Hours:
Monday – Friday: 8:00 AM – 6:00 PM PT